Home About Coverage Contact
Get Quote
Home/About

About CapeCover

Coverage works best when the conversation starts with what matters, not with a quote form. That shift sits at the heart of how I handle every policy review.

Slow, careful, and built around the household

Most coverage conversations start with a quote form. Mine starts with a blank page and a question: what would actually hurt if it went unprotected? That single shift changes how I weigh every line of a policy.

It means I evaluate liability limits against real assets, weigh deductibles against actual savings, and skip the add ons that sound useful but rarely pay out. It means I ask about the doctors that matter before chasing the lowest premium. I treat coverage as a structure, not a transaction.

At the end of it, a household walks away with a policy that maps to actual life. Not a generic plan built for someone else, and not a stack of paperwork to be filed away and forgotten.

Explore Coverage
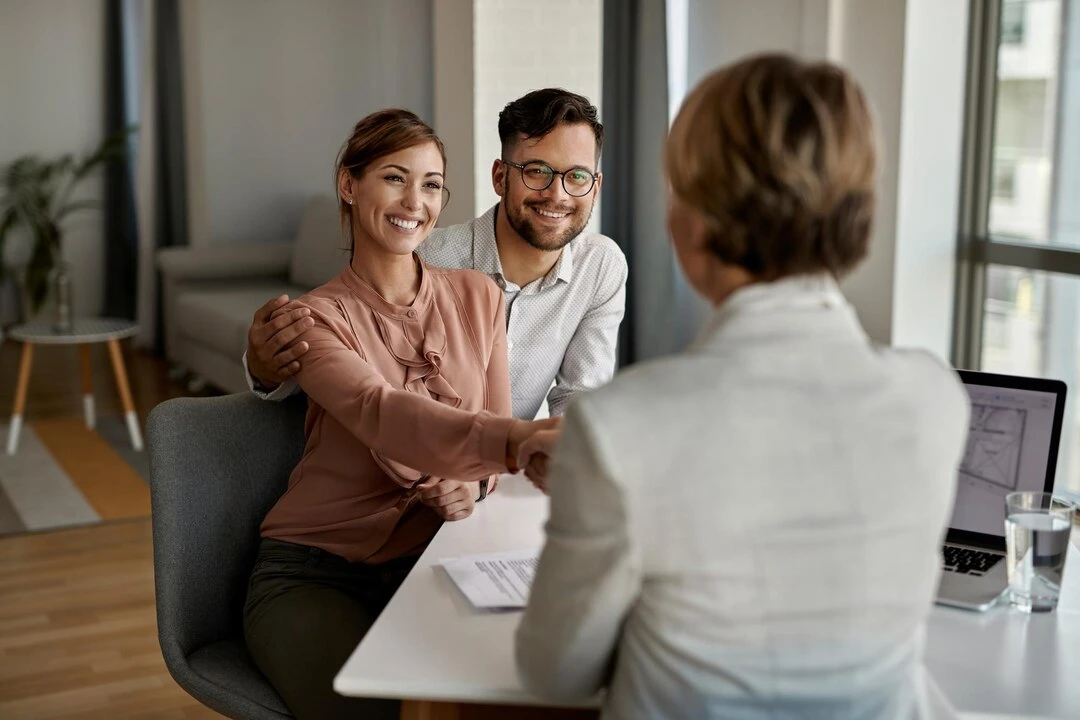
A calm coverage review at the kitchen table

The ideas that shape every conversation

Three principles that hold true across every coverage type and every policy review.

Start With The Household

Coverage decisions sit downstream of life. Assets, dependents, debts, health, travel patterns. The shape of those things sets the shape of the policy.

Right Size, Never Oversell

I cut the add ons that rarely pay out. I raise the limits that fall short of the real exposure. The right number is the one that holds up at claim time.

Revisit Every Year

A policy signed long ago covers the life from long ago. An annual pass keeps the structure aligned with what life actually looks like now.

From open question to a policy that holds up

A short walk through how a coverage review moves from first conversation to final decision.

01

Listen First

I open each review with what matters in the household. Assets, dependents, current policies, recent changes. No quote form to start.

02

Map The Exposure

I weigh each coverage line against what would actually hurt if it went unprotected. Gaps and overlaps surface in plain language.

03

Compare Carriers

I pull quotes across multiple carriers, then narrow by claim reputation, network depth, and the hidden clauses that often go unread.

04

Review Yearly

Life shifts. A renovation, a new driver, a fresh prescription. An annual check catches drift before it becomes a claim problem.

Common questions about the approach

The questions that surface most often once a coverage review actually begins.

Independent. I pull quotes across multiple carriers, and the final choice lands on whichever fits the household best, not whichever pays the highest commission.

It depends on how many coverage lines need to be examined. I never rush, and nothing gets signed at the first call.

No. I review coverage line by line. If an existing policy already holds up, it stays. The point is fit, not movement for its own sake.

Nothing. Reviews are free. The carrier pays me when a policy gets placed, and I disclose that up front.

It stays within the scope of the coverage inquiry. Details only move to a carrier with prior consent, and I never sell anything to outside marketers.

Coverage that fits takes one conversation

No endless quote forms. No voicemail tag. A direct look at what needs protecting and what it actually takes.

Get Quote